Mercado Pago: cuenta digital
- 8.19KReviews
- 4.8
- Developer
- Mercado Libre
- Released
- Dec 9, 2014
Screenshots
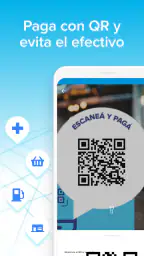
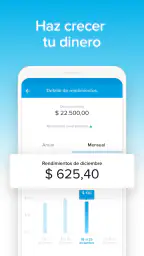
I have used Mercado Pago: cuenta digital as a practical money app rather than as a simple wallet, and that distinction matters. It is designed to bring everyday payments, QR purchases, credit tools, and card access into one place. In my experience, its biggest appeal is convenience: I can open one app when I want to pay in a shop, check available money, or manage a purchase without moving between several financial services.
At the same time, I would not describe it as the perfect replacement for every bank or payment method. It works best for people who regularly interact with Mercado Libre’s financial ecosystem and want a straightforward mobile account. Someone who needs a full traditional banking relationship, highly specialized investment tools, or complete control over every financial product may find its scope narrower than expected.
How Mercado Pago feels in everyday use
The app comes from Mercado Libre and belongs firmly in the finance category. It is free to install, aimed at everyone from a content-rating perspective, and has been available since December 9, 2014. Its current version is 2.454.3, with support beginning at Android 6.0. Those details show that this is a mature product rather than a newly launched experiment, although the experience can still vary depending on the country and the services available to a particular account.
Its scale is immediately noticeable. The app has a 4.8 average from around 14 million ratings and more than 100 million installs. I see those figures less as a guarantee that every user will love it and more as evidence that Mercado Pago has become a familiar part of daily commerce for a very large audience.
The central idea is simple: keep several payment-related tasks together. The app can be used for QR payments, access to a line of credit, and card-related activity. That combination is more useful than a wallet that only stores money, because it gives the user different ways to complete a purchase when one option is inconvenient.
For example, imagine I am buying lunch at a small business that accepts QR payments. Instead of handling cash or using a physical card, I can open the app, scan the code, review the amount, and approve the transaction. Later, I can return to the same account to inspect the movement. That flow is quick when the merchant’s code works properly and my account is already configured.
The important practical advantage is continuity. A payment is not isolated from the rest of my activity; it sits alongside the account, card, and credit tools. This makes the app especially attractive to people who shop through Mercado Libre or receive payment-related activity connected to that ecosystem.
What has changed for a mature financial app
The current version number, 2.454.3, suggests an actively maintained application rather than a frozen utility. I would interpret that as a sign of ongoing refinement, not proof that every update changes the product dramatically. Financial apps often evolve through adjustments to navigation, security, account flows, and compatibility, and those improvements can be valuable even when they are not visually impressive.
For an existing user, the most meaningful evolution is the way separate financial tasks can live in one mobile experience. The app is not limited to sending money or scanning a code. Its identity now covers a digital account, QR payments, credit access, and a card. That broader role can reduce the need to remember which service handles each transaction.
This consolidation also changes how I think about the app. I do not open it only when I am at a checkout. I might use it to check whether a payment went through, review a credit-related option before buying, or decide whether the card or QR route is more convenient. The benefit is not one spectacular feature; it is the reduced friction between related tasks.
Still, I would avoid assuming that every account receives exactly the same tools. Financial products can depend on location, eligibility, account status, and local availability. The app may present a credit option to one person while showing a different set of choices to another. That is normal for this kind of service, but it is worth remembering before treating the store summary as a promise of identical access for everyone.
Who benefits most from the combined account
I think the strongest audience is someone who wants a convenient digital account for routine commerce. If I frequently buy online, pay participating businesses with QR codes, or prefer to keep payment activity on my phone, Mercado Pago has a clear advantage over using several disconnected tools.
It is also useful for people who dislike carrying a physical wallet everywhere. A phone can handle the payment step, while the card option provides another route when a QR purchase is not suitable. That flexibility is more practical than relying on a single method, especially when I am moving between online purchases and in-person transactions.
Small sellers and independent workers may also appreciate having payment activity close at hand, particularly when their customers use QR codes. I would not treat the app as a complete replacement for every business-finance system, but it can make ordinary collection and payment interactions feel less fragmented.
The app is less compelling for someone who wants a conventional bank account with a broad branch-based service model. It may also be a poor fit for a user who avoids app-based financial management, does not want credit options appearing alongside payments, or prefers to keep shopping and finance entirely separate.
There is another trade-off: convenience can encourage impulsive decisions. When payment, credit, and card tools appear in the same place, buying may feel effortless. I recommend checking the funding source and the final amount before confirming, especially when using credit rather than money already available in the account.
A realistic payment routine
My preferred way to use the app is to prepare before I need it. I would sign in, make sure the account details are current, review the available payment methods, and understand where transaction activity is displayed. That preparation matters because a checkout is the worst moment to discover that I need an extra verification step or that my preferred method is unavailable.
At the store, I would scan the merchant’s QR code and pause before approving anything. The useful habit is not merely scanning quickly; it is checking the recipient and amount on the confirmation screen. QR payments are convenient, but convenience should not eliminate the final review.
Afterward, I would return to the account activity and confirm that the transaction appears as expected. This is a small workflow, but it gives me a reliable record and helps separate a completed payment from an abandoned or interrupted attempt. It is one of the app’s practical strengths that these tasks are close together rather than spread across separate services.
If I were considering the credit feature, I would treat it as a decision tool rather than an automatic invitation to spend. I would compare the repayment obligation with the original purchase and avoid using credit simply because it is visible. The app can make access convenient, but the responsibility for understanding the commitment remains with me.
Where it compares well with usual alternatives
Compared with cash, Mercado Pago is easier to track digitally and more flexible for QR purchases, but it depends on a working phone, an active account, and merchant acceptance. Cash remains useful when I want a transaction that does not depend on an app interface or mobile connectivity.
Compared with a traditional bank app, Mercado Pago feels more closely tied to commerce. Its strength is the connection between paying, shopping, card use, and credit-related activity. A bank may be a better choice for users who prioritize a broader account relationship, while this app is more appealing when quick purchasing and digital payment are the main goals.
Compared with a basic wallet, it offers a wider financial center through its account, QR payments, card, and credit functions. That breadth is convenient, but it can also make the interface feel busier. A person who wants only a minimal way to send or receive money may prefer a simpler tool.
Compared with using a physical card directly, QR payment can be faster in participating stores and avoids taking out the card. The card, however, remains valuable as a backup when a merchant does not support QR or when I prefer a conventional checkout. In my view, the best approach is not choosing one method permanently but keeping both available and checking which is appropriate.
Small habits that improve the experience
My first recommendation is to treat the confirmation screen as a security checkpoint. I would verify the amount and recipient every time, even when the purchase is familiar. This takes only a moment and is more useful than assuming a scan always points to the intended destination.
Second, I would separate available money from borrowing in my own mental budget. The presence of a credit option can make a purchase appear affordable when the repayment is the real cost to plan for. Using a simple note or personal budget outside the app can make that distinction clearer.
Third, I would use the activity history as a reconciliation tool rather than merely an archive. At the end of a shopping day, checking recent movements can reveal whether a payment was completed, duplicated, or left pending. This is particularly helpful when a checkout screen closes unexpectedly or the network connection is unstable.
Fourth, I would keep the app updated through the official mobile-store channel and avoid relying on an old installation indefinitely. The current version is 2.454.3, and maintaining a current build is sensible for a financial app because account access and payment flows need to remain compatible with the device environment.
Finally, I would decide in advance which payment method I want to use before reaching the checkout. If I already know whether I am paying from the account, using the card, or considering credit, I am less likely to make a rushed choice under pressure.
Remaining friction and sensible limits
The biggest limitation is that the app brings several financial functions together without making every decision simple. A first-time user may understand how to scan a QR code but feel less confident about the difference between account money, card usage, and credit. The interface can make access easy; it cannot replace careful reading of the terms attached to a financial choice.
Another point of friction is dependence on the surrounding ecosystem. QR payments work best where merchants support them, and card or credit availability may differ by account. That means the app is not equally useful in every location or for every person. I would keep another payment method available instead of assuming Mercado Pago will always be accepted.
People who value a highly specialized banking dashboard may also find the experience too commerce-focused. The app’s strength is bringing payment-related actions close together, not necessarily offering every service that a full bank or dedicated investment platform might provide.
Privacy and account security deserve the same attention I would give any financial app. I would use a secure device lock, avoid approving transactions while distracted, and never share verification information with someone who claims to be helping. These are not reasons to reject the app; they are basic conditions for using a digital account responsibly.
What I would watch as an existing user
For future updates, I would pay attention to whether navigation becomes clearer as more financial tools are added. A mature app can become more capable while also becoming harder to understand. The best evolution would preserve quick QR payments while making credit, card, and account choices visibly distinct.
I would also watch how reliably the app communicates transaction status. When money is involved, users need to know whether a payment is complete, waiting, or unsuccessful. Clear activity records and unambiguous confirmation messages matter more to me than decorative interface changes.
Compatibility is another practical concern. Since the app supports Android from version 6.0 onward, it remains accessible to many older devices, but individual phones can still differ in speed and system behavior. On an older handset, I would allow extra time before a checkout and avoid closing the app immediately after confirming a payment.
Most importantly, I would judge future changes by whether they improve control rather than simply adding more options. A useful update should help me understand where money is going, which payment method I am selecting, and what obligation I am accepting. More features are valuable only when they remain easy to interpret.
My recommendation
Mercado Pago is a strong choice for people who want a free finance app centered on everyday digital commerce. Its combination of QR payments, a digital account, card access, and a line of credit gives it more practical range than a basic wallet. The large user base and long availability also make it feel like an established service rather than a temporary payment experiment.
I would recommend it to a friend who shops through Mercado Libre, encounters QR payments regularly, or wants several payment routes in one mobile account. I would suggest starting with simple account-funded payments, learning where activity is recorded, and only then exploring card or credit options.
I would not recommend relying on it as the only financial service for someone who needs a full traditional bank relationship or who prefers to avoid app-based money management. Even for suitable users, a backup payment method and careful review of every confirmation remain sensible.
Overall, I find the app most valuable when it reduces ordinary friction without encouraging careless spending. Used deliberately, it can turn the phone into a practical payment center. Used automatically, its convenience may make financial decisions feel easier than they really are. That balance is the key to getting the most from Mercado Pago.
Highlights
- Fast transfers to contacts and bank accounts
- Convenient QR payments at participating stores
- Useful bill payment and mobile recharge options
- Virtual card available for online purchases
- Clear transaction history helps track spending
Limitations
- Some features and fees vary by country
- Support response times may be slow during busy periods
- Account verification can require extensive personal information
- Cash withdrawal availability depends on local networks
- Some promotions have conditions that are easy to overlook
Frequently Asked Questions
What is Mercado Pago: cuenta digital, and what can I use it for?
Mercado Pago: cuenta digital is a mobile wallet and digital financial account designed for managing everyday money from your phone. After registering, users can typically receive and send funds, pay bills, scan QR codes at participating stores, make online purchases, recharge mobile credit, and review their transaction history. Available services may differ depending on your country, account status, and local regulations.
Is Mercado Pago: cuenta digital safe to use for payments and money transfers?
Mercado Pago includes security features such as account passwords, identity verification, transaction notifications, and additional authentication options on supported devices. However, users should still protect their login details, avoid sharing verification codes, and download the app only from official stores. Before confirming a payment or transfer, carefully check the recipient, amount, and any applicable fees.
Do I need a bank account or credit card to use Mercado Pago?
You can generally open and use a Mercado Pago digital account without having a traditional bank account, although registration normally requires personal information and identity verification. Depending on your location, you may add money through bank transfers, debit cards, cash-based methods, or other supported options. Some features, such as credit or installment services, may require separate approval.
Are there fees for using Mercado Pago: cuenta digital?
Many basic actions, including opening an account and making certain payments, may be free, but fees can apply depending on the operation. Costs may vary for card funding, withdrawals, transfers, currency conversion, merchant services, or credit-related products. The app generally displays the applicable charge before confirmation, so review the final amount and the current terms in your country.
Can I use Mercado Pago if I live outside Latin America or travel abroad?
Mercado Pago services are primarily designed for specific Latin American markets, and account availability, payment methods, currencies, and features depend on the country where the account was created. You may not be able to register from an unsupported region or use every function while traveling. Check the local version of the app and its regional terms before relying on it abroad.


